Strict budgets fail when they eliminate life's pleasures. The traditional "zero-based" budget often feels like a punishment, forcing consumers into extreme frugality until burnout hits. Industry data reveals that over 75% of online shopping carts are abandoned due to unbudgeted costs, while nearly 64% of consumers actively search for promo codes online before completing a purchase to stretch their discretionary spending power.
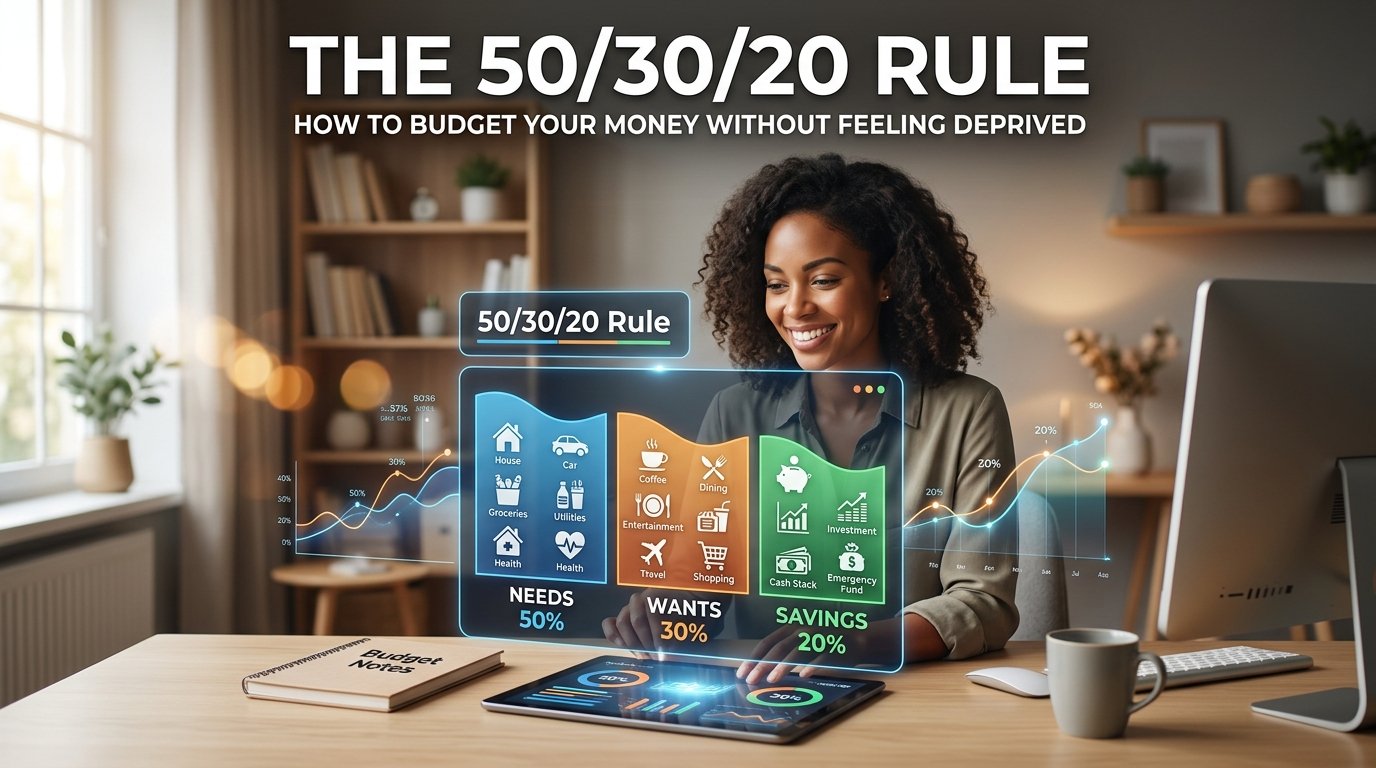
The 50/30/20 rule solves the budget burnout problem by baking fun directly into your financial architecture. Instead of cutting out every non-essential purchase, this framework divides your net take-home pay into three clear, non-negotiable buckets:
50% Needs: Essential fixed survival costs (rent, utilities, basic groceries, debt minimums).
30% Wants: Discretionary spend (dining out, entertainment, shopping, leisure).
20% Savings & Extra Debt: Wealth building (emergency funds, retirement, investments, principal debt paydown).
By combining this structured framework with aggressive online shopping discounts, you lower your fixed costs and artificially inflate the spending power of your 30% "Wants" bucket—allowing you to buy what you love without overspending.
How to Calculate and Execute Your 50/30/20 Breakdown
Step 1: Establish Your After-Tax Net Income
Start with your net monthly income—the exact dollar amount deposited into your bank account after taxes, health insurance, and pre-tax retirement deductions.
Example: If your monthly net take-home pay is $4,000:
Needs Bucket (50%): $2,000 maximum
Wants Bucket (30%): $1,200 maximum
Savings Bucket (20%): $800 minimum
Step 2: Cap the 50% "Needs" Bucket
Your needs are expenses you cannot avoid without serious real-world consequences: shelter, basic food, healthcare, transportation, and minimum debt obligations.
The Problem: Housing costs and inflation frequently push this bucket past 50%.
The Solution: Optimization. Lowering monthly recurring costs—like car insurance, internet service, or staple grocery orders—instantly frees up margin. Applying category-specific digital coupons on bulk grocery pickups or utility bill sign-ups can drop your base fixed costs back under the 50% threshold.
Pro Tip: Never confuse a "Need" with a premium "Want" disguise. Organic artisanal groceries are a Want; basic staple food is a Need. High-speed gigabit fiber internet is a Want; basic functional home broadband is a Need.
Step 3: Protect and Maximize the 30% "Wants" Bucket
This is the secret weapon of the 50/30/20 rule. The 30% bucket exists to prevent psychological fatigue. You are explicitly allowed—and encouraged—to spend this money on apparel, tech gadgets, travel, and dining out.
The key to mastering this bucket is spending power multiplication. If you have $1,200 allocated for wants, using verified promo codes and stackable store vouchers allows that $1,200 to purchase $1,600 to $1,800 worth of retail value.
$4,000 MONTHLY NET TAKE-HOME PAY ┌───────────────────┬───────────────────┐ │ │ │ ▼ ▼ ▼ 50% NEEDS 30% WANTS 20% SAVINGS ($2,000) ($1,200) ($800) ───────── ───────── ─────────── • Rent / Mortgage • Shopping & Tech • Emergency Fund • Utilities • Dining & Leisure • Investments • Basic Groceries • Travel & Gear • Debt PaydownStep 4: Automate the 20% "Savings & Debt" Allocation
The final 20% is non-negotiable for long-term wealth creation. Set up automatic bank transfers on payday that route 20% of your earnings directly into high-yield savings accounts or investment portfolios before you ever see it.
Pro Warning: Treating savings as "whatever money is left over at the end of the month" is a guaranteed path to a $0 balance. Always pay your savings bucket first.
Comparison of Budgeting & Discount Coupon Strategies
| Strategy / Method | Effort Level | Primary Target Bucket | Expected Financial Impact |
| Verified Coupon Hubs | Low | 30% Wants / 50% Needs | 15% – 35% Off Retail |
| Automated Savings Transfers | Low (Set & Forget) | 20% Savings | Guarantees 20% Wealth Rate |
| Cart Abandonment Hacks | Medium | 30% Wants | 10% – 20% Instant Promo Code |
| Bulk Grocery / BOGO Bundling | Medium | 50% Needs | 20% – 40% Lower Food Costs |
| Newsletter Signup Vouchers | Low | 30% Wants | 10% – 15% First-Order Code |
Advanced Coupon Strategies to Stretch Your "Wants" Bucket
To get 50% to 100% more value out of your 30% discretionary budget, implement these tactical online shopping discounts at checkout:
Source Tested Codes via Verified Deal Portals: Avoid broken discount boxes, dead links, and expired vouchers. Visit the
FavourSaver Verified Coupon Hub Master the Cart Hold Technique: Log into your retail account, place your target apparel or tech item in the cart, and navigate away from the tab. Merchants routinely send follow-up emails with exclusive 10% to 20% off discount codes to capture the sale.
Execute Promo Stacking: Always test multiple code entries. Apply a primary percentage-off coupon first, followed by a free shipping voucher or store rewards redemption to double up on savings at checkout.
Final Verdict & Call to Action
The 50/30/20 rule proves that you don't need to sacrifice your lifestyle to build lasting wealth. By capping your fixed needs at 50%, putting 20% into automated savings, and using smart coupon strategies to stretch your 30% wants bucket, you get total financial control without feeling deprived.
Ready to make your discretionary budget go twice as far? Head over to